AugurMax Asset Allocation Changes 2026-09-30
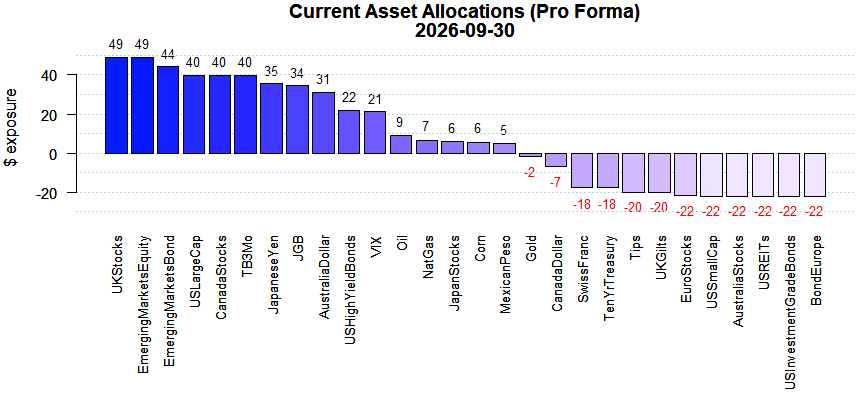
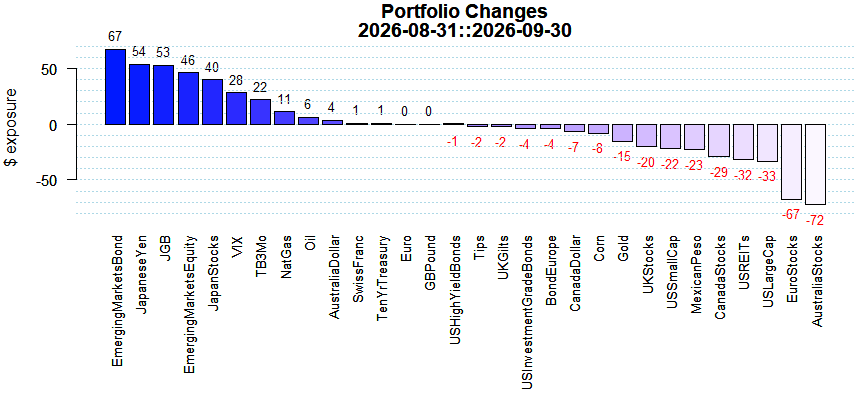
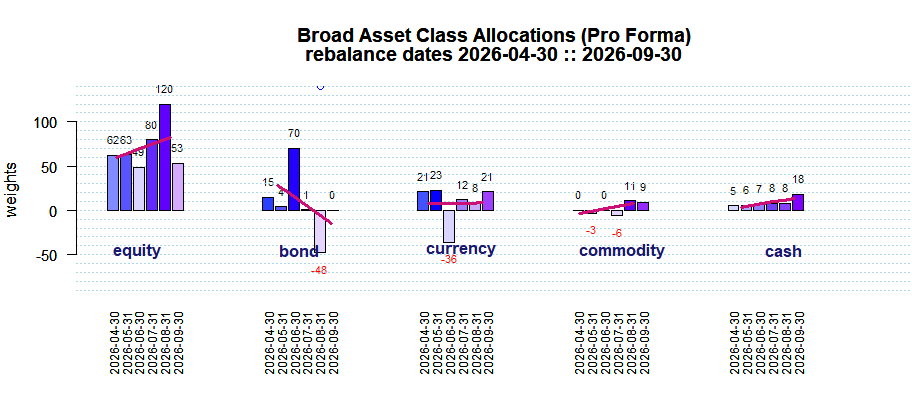
Equity exposure was reduced substantially at the end of September as stocks around the globe slipped — equities were broadly reduced but some, like Emerging Markets and Japan, were added to. VIX exposure moved up a fair amount and because of its negative correlation with equities, its increase reduces portfolio risk. While posting a negative return for the month, stocks still outperformed the other broad asset classes (except cash). Current stock exposures are in line with their longer-term average. Bond exposures moved up considerably to a flat exposure and are still well below their long-term average weighting. The prescribed Currency exposure moved up marginally after a generally bad showing in September. Commodity exposure did not change much and commodities remain above their longer term weighting.
Equity reductions were widespread as the Euroland, Australia, and US Large Caps got the biggest cuts. Japan and Emerging Markets were the only markets raised. Interest sensitive US REITs were throttled back and are now a big short.
The big reallocation to bonds was highly concentrated as only Emerging Markets and JGBs were added to. Cash exposure was bumped up quite a bit.
There were quite a few shifts within commodities where Gold was brought down while NatGas and Oil were pushed up.
Currency returns were up down big across the board in September as money continued to flow into the US Dollar. The Mexican Peso was cut big time while raises happened in the Euro and the Mexican Peso.
September’s global stock slump was broad but Japan and Emerging Markets advanced. Growth dramatically outperformed value stocks after also beating in August as once again tech stocks took the lead. Bonds returns were all down around the globe with JGBs the relative outperformer. EM Bonds and US TReasuries fared the worst. US Treasuries underperformed US Tips hinting at a more worrisome inflation situation (see breakeven inflation rates). US Large Caps are now more than 57% above their April 2025 lows (see worst drawdowns) and hedge funds reported negative September returns. The prescribed changes herein are largely influenced by our ECO methodology. Performance results (on a stand-alone basis) for assets like Gold and others using our ECO metrics are shown here.